Hi ComCons,
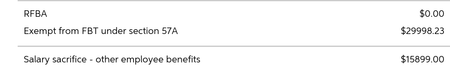
Thanks for the screenshot. These two STP labels can be confusing, but having both appear can be correct. Where a benefit is both salary-sacrificed and a reportable fringe benefit, the ATO requires both to be reported. They represent different things:
- Salary sacrifice – other employee benefits: the actual salary or wages sacrificed for non-super benefits during the 1 July–30 June financial year, without grossing up. In MYOB, this is an ATO reporting category assigned to the deduction, rather than the ledger account used to pay it out.
- Exempt from FBT under section 57A: the grossed-up reportable value of applicable benefits for the 1 April–31 March FBT year, reported in the income year ending the following June.
MYOB’s ATO reporting categories guide also explains the salary-sacrifice deduction category. It's also best to have your accountant check the categories before making any changes.
Cheers,
Doreen